
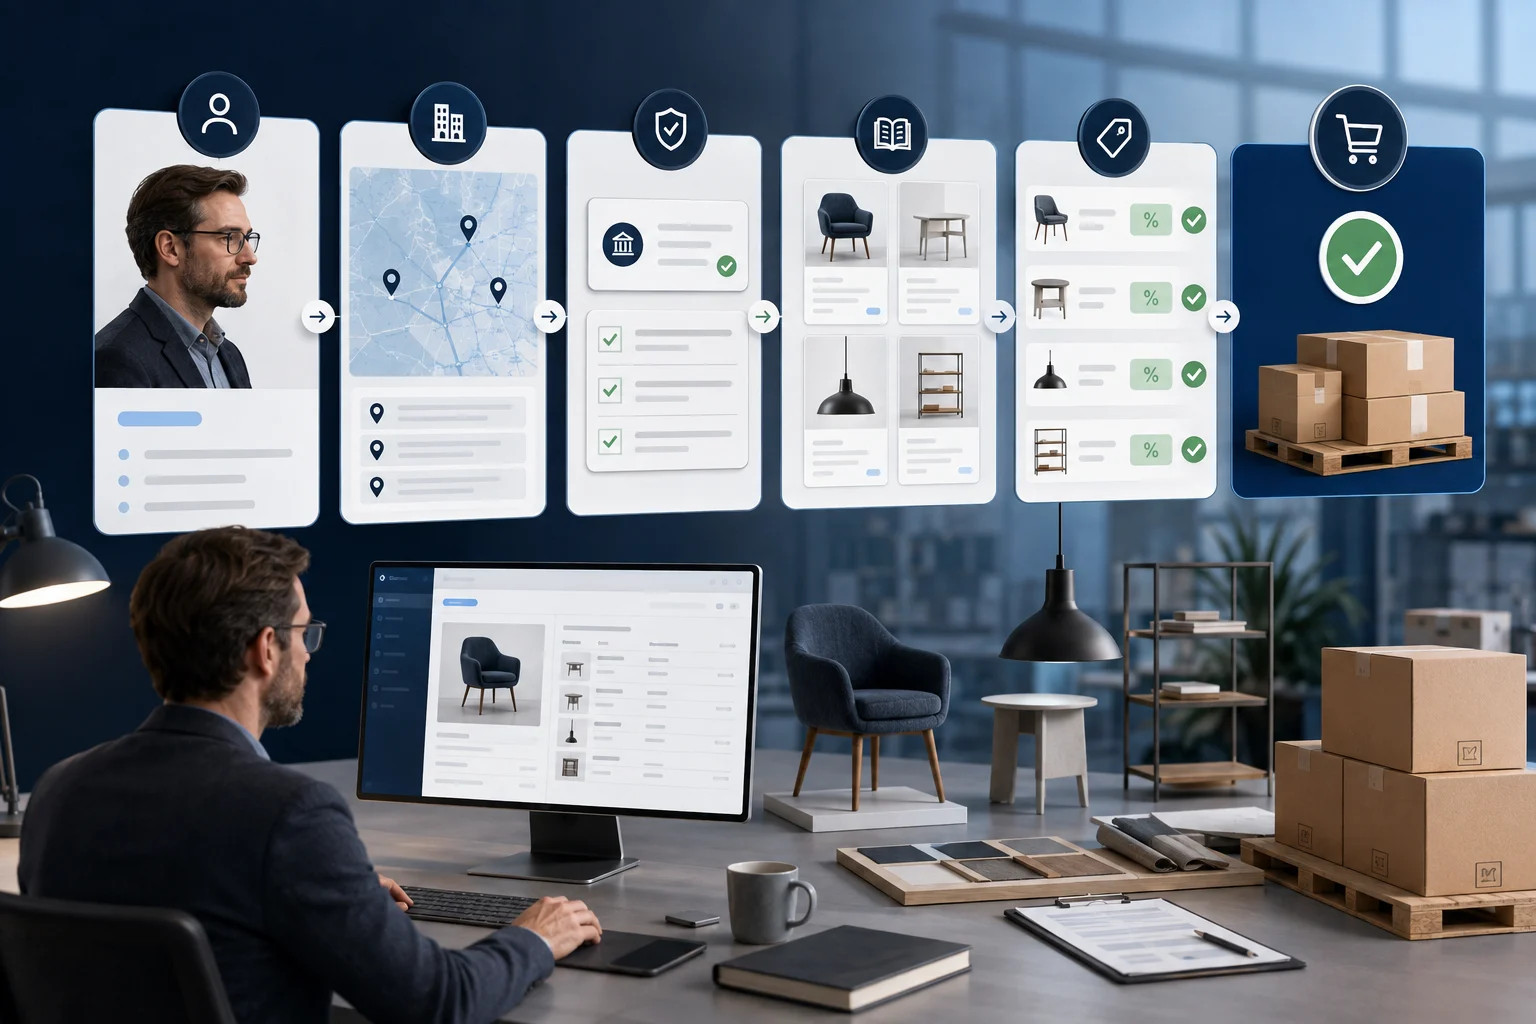
What we have seen in Shopify B2B work is this: teams often treat account approval as the finish line, then discover that the buyer sees the wrong price, cannot ship to a branch, receives retail messaging or has no idea how to order. Shopify wholesale customer onboarding should connect commercial approval to a verified first-order experience.
Contact StoreBuilt if trade accounts still depend on inbox threads and manual price fixes.
Table of contents
- Keyword decision
- Choose the account model
- Design the application
- Separate approval decisions
- Configure the buying experience
- Measure first-order activation
- StoreBuilt point of view
Keyword decision
Primary keyword: Shopify wholesale customer onboarding. Secondary intents include Shopify B2B UK, trade account application and B2B ecommerce onboarding. The intent is solution evaluation and implementation, sitting between middle and bottom funnel. Competitor libraries explain Shopify B2B features and platform choice, but the operational handoff from application to first valid order is less thoroughly served. StoreBuilt can win with a practical workflow that naturally supports its Shopify Plus and B2B service without cannibalising that commercial page.
Choose the account model
Decide what an account represents before building a form. A sole trader with one address is different from a national buyer with head-office billing, regional delivery locations and several purchasers. Define company, location, contact, role, catalogue, currency, payment and tax relationships.
Shopify’s native B2B capabilities on eligible plans can model companies, locations, contacts, catalogues and payment terms. Other merchants may use a wholesale app or a separate storefront. Choose against the operating model, not a feature screenshot.
| Requirement | Question to resolve | Risk if ignored |
|---|---|---|
| company structure | who owns pricing and credit? | duplicate or conflicting accounts |
| locations | which branches may buy and receive? | wrong delivery or tax treatment |
| contacts | who orders, approves and administers? | excess access |
| catalogue | which products and prices apply? | margin leakage |
| payment | prepaid, card, deposit or terms? | uncontrolled credit |
| fulfilment | stock, minimums and lead times? | promises operations cannot meet |
Document exceptions such as export customers, franchisees, distributors, staff buyers or regulated product access. If exceptions are common, the model is incomplete.
Design the application
Ask only for information needed to make a decision or create the account. Typical fields include registered and trading name, company number where applicable, VAT information when relevant, billing and delivery addresses, website, buyer contact, expected products and order profile. Explain why supporting evidence is requested and how data will be used. This is operational guidance, not legal or tax advice; validate obligations with qualified advisers and current UK regulator guidance.
Use conditional questions instead of one intimidating form. A prepaid buyer should not complete a full credit application. An export customer may need different delivery and tax questions. Save a clear consent record where marketing permission is requested, keeping it separate from essential account communication.
Set expectations immediately: application received, expected review time, missing evidence, approval outcome and next steps. Avoid exposing internal notes in customer notifications. Give applicants a reference so support can find the case.
An anonymous UK supplier had applications arriving through a generic contact form. Sales copied details into Shopify, finance separately checked credit, and buyers were sometimes invited before prices were assigned. The redesigned sequence used one application record, explicit approval stages and an activation checklist. The important gain was consistent ownership, not an invented conversion statistic.
Separate approval decisions
“Approved” is too broad. Use distinct statuses for identity checked, commercial fit approved, catalogue assigned, tax reviewed, payment method approved, credit approved and account activated. A buyer can be commercially approved for prepaid ordering while finance continues a credit review.
| Decision | Typical owner | Required evidence | Output |
|---|---|---|---|
| business identity | sales operations | application and public records | verified entity |
| product access | commercial lead | channel and territory rules | catalogue |
| pricing | commercial or finance | agreed tier and currency | price list |
| credit | finance | approved policy and checks | limit and terms |
| delivery | operations | address and service capability | shipping rules |
| activation | account owner | completed test | buyer invitation |
Apply least-privilege access. Buyers should see only relevant companies and locations. Staff who edit terms or catalogues need controlled permissions. Record who made each decision and when, especially for manual overrides.
Explore Shopify B2B integrations when CRM, ERP and Shopify all participate in approval.
Configure the buying experience
Before inviting the buyer, confirm the correct catalogue, currency, quantity rules, minimum order value, tax display, delivery methods and payment options. Test products that are excluded, out of stock, made to order or restricted by location. Decide how discounts interact with contracted prices; retail discount codes should not accidentally stack on trade terms.
Make the first session self-explanatory. The welcome message should identify the company and location, sign-in method, ordering route, delivery expectations, payment arrangement and support contact. Link to concise information on pack sizes, lead times, returns, samples and invoice access.
Run a complete acceptance order for each meaningful account type. Validate:
- the correct contact can sign in;
- only authorised company locations appear;
- product access and prices match the agreement;
- quantity and minimum rules behave correctly;
- tax and delivery are appropriate;
- payment or purchase-order input follows policy;
- emails contain the right B2B language;
- the order reaches ERP, warehouse and finance correctly.
Do not rely on an admin screenshot of the assigned catalogue. The buyer-facing checkout and downstream order are the acceptance test.
Measure first-order activation
Track application completion, review age, rejection reason, activation time, invitation acceptance, first-order time and support contacts before first purchase. Segment by buyer type and avoid celebrating fast approval if orders later require correction.
Create an exception queue for duplicate businesses, unmatched VAT details, unapproved ship-to addresses, catalogue conflicts, missing payment terms and failed invitations. Every exception needs an owner and expiry date. Review repeated causes monthly and improve the form or integration rather than adding more manual notes.
Use CRM stages to help sales, but keep Shopify’s active commercial configuration authoritative for what the buyer can actually purchase. Synchronise stable identifiers so a company is not recreated whenever a new contact joins.
StoreBuilt point of view
StoreBuilt believes B2B onboarding is successful only when an authorised buyer completes a correct order without backstage rescue. A beautiful application form is irrelevant if pricing, permissions or fulfilment fail later. Model the company properly, separate approval decisions, and test from invitation through downstream operations. That turns wholesale ecommerce from a collection of exceptions into a service buyers can trust.
Plan a Shopify B2B onboarding workflow with StoreBuilt.
When buyers need to hand a selection to a colleague, our Shopify shareable-cart guide distinguishes product links, saved baskets and controlled quotes.