
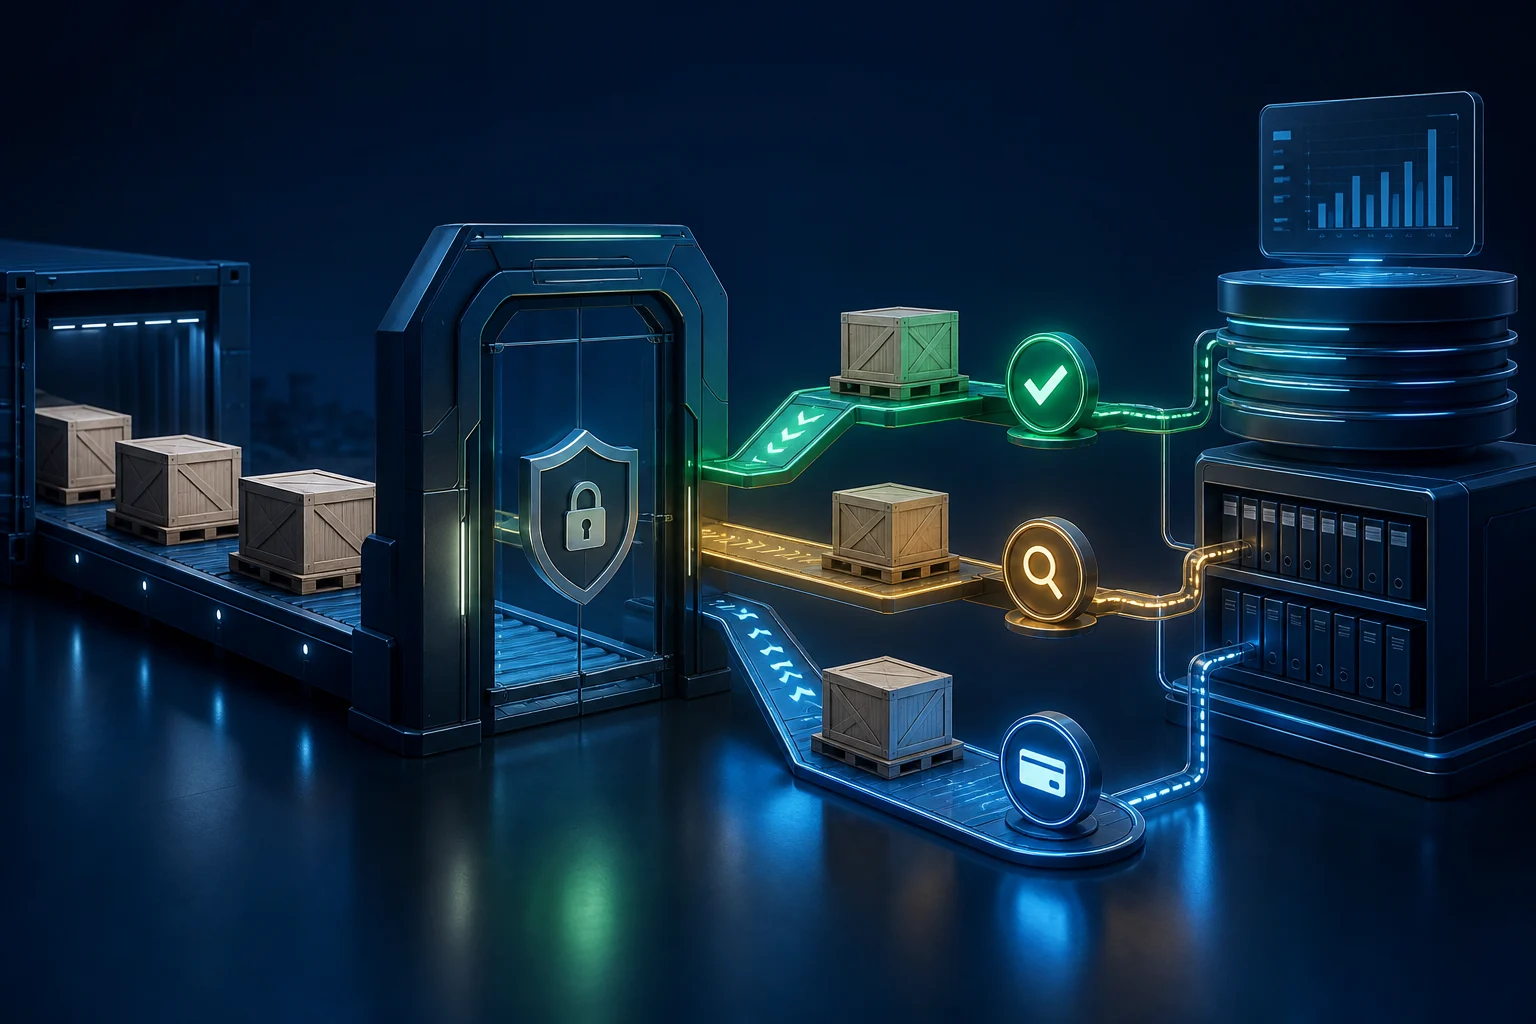
What we have seen is this: wholesale ecommerce becomes risky when a familiar offline exception is translated into an invisible online shortcut. A buyer places an order on terms, open invoices are held in another system, a sales colleague promises an override and stock is released before finance sees the total exposure.
Shopify B2B can make purchasing easier, but credit control still needs a designed operating model across storefront, admin, ERP and people.
Table of contents
- Keyword decision
- Separate terms, limits and available credit
- Choose a source of truth
- Design the order decision
- Handle holds and overrides visibly
- Test timing, failure and reconciliation
- Use a practical control matrix
- StoreBuilt point of view
Keyword decision
| Decision | Direction |
|---|---|
| Primary keyword | Shopify B2B credit limits |
| Secondary keywords | Shopify payment terms UK, B2B ecommerce approval workflow, Shopify Plus wholesale |
| Search intent | Control trade-credit purchasing through Shopify B2B |
| Funnel stage | Bottom |
| Page type | B2B workflow and integration guide |
| Why StoreBuilt can win | The answer requires storefront, order, ERP, finance and exception-flow implementation knowledge |
UK Shopify agency content explains B2B features and wholesale benefits well. The implementation gap is how credit exposure is governed when orders, invoices and payments cross systems.
Separate terms, limits and available credit
Define the nouns before building logic. Payment terms set a due date or payment schedule. A credit limit states the maximum approved exposure. Available credit is the limit less whatever the business counts as exposure: unpaid invoices, unfulfilled orders, authorised orders, disputed balances or some combination.
Finance must define when exposure begins and ends. Does a draft order reserve credit? Does a cancelled but unreconciled order still count? How are credit notes, deposits, part-payments and multi-currency accounts treated? The ecommerce team should not infer these rules from a spreadsheet label.
Group buyers by company location where commercial terms, tax, currency, delivery or purchasing authority differ. A parent company may have one overall facility or separate limits per branch; the data model should reflect the real agreement.
Choose a source of truth
Nominate one system as authoritative for approved limit, current exposure and hold status. In many established businesses that will be the ERP or finance platform. Shopify may display or act on the decision without becoming the accounting ledger.
Document each field, direction and update trigger. Record limit, currency, payment term, hold reason, review date and last successful synchronisation. Treat missing or stale credit data as a known state, not as approval.
Decide the safe behaviour if the source is unavailable. For a low-value repeat account, the business might accept a controlled fallback. For a high-value order, it may hold the order for review or require immediate payment. The decision belongs to finance and risk owners.
Our Shopify Plus and B2B service helps teams translate commercial account rules into a usable buying journey.
Design the order decision
Map the decision at the right point. Checking only when a buyer logs in may leave the result stale by checkout. Checking after fulfilment is too late. The useful control often combines an early message with a final decision before order release.
The buyer experience should distinguish:
- approved on terms and within available credit;
- approved account but order requires finance review;
- temporarily held because of overdue balance;
- above limit with deposit or card-payment alternative;
- missing or stale account data;
- buyer without permission to place the order.
Avoid exposing sensitive account information to the wrong company contact. Show enough to explain the action and give a route forward, while respecting account roles and internal privacy decisions.
Handle holds and overrides visibly
A held order needs a state, owner and clock. Notify the buyer that the request is being reviewed, notify the internal queue with the reason and prevent downstream systems from interpreting the order as ready to fulfil.
Overrides should record approver, amount, reason, expiry and affected order. A permanent limit change is different from a one-order exception. Do not let a note or manual tag become an undocumented credit policy.
An anonymous StoreBuilt integration discovery found that teams used “on hold” to describe several unrelated states: credit review, stock wait, price approval and fraud review. Separating those states made ownership and customer communication clearer before any automation was written.
Test timing, failure and reconciliation
Run scenarios with two buyers ordering against the same company facility, partial fulfilment, cancellation, refund, credit note, payment posted late, limit reduction and an integration outage. Test duplicate and out-of-order messages so an older update cannot reopen credit incorrectly.
Reconcile daily or at a frequency proportionate to risk. Compare Shopify orders held or released with the finance system’s exposure and payment state. Alert on stale customer data, unmatched company identifiers and orders stuck without an owner.
Security matters too. Use least-privilege service access, protect financial fields, log administrative changes and remove departing users promptly. For integration implementation, see our Shopify apps, integrations, and automation service.
Use a practical control matrix
| Decision | Owner | Safe failure |
|---|---|---|
| Approve or change limit | Finance | Keep previous approved limit until reviewed |
| Assign payment terms | Finance/commercial | Require immediate payment or review |
| Check available credit | Authoritative finance system | Hold high-risk order |
| Release fulfilment | Operations after approved state | Do not allocate as ready |
| Override one order | Named approver | Expiring, logged exception |
| Reconcile orders and balances | Finance operations | Alert and investigate mismatch |
The precise policy varies by business. This is workflow guidance, not financial or legal advice; credit agreements, collections and customer communications should be reviewed by the appropriate UK advisers.
Review the policy on a calendar as well as after an incident. Account risk, seasonality, ownership and purchasing patterns change. A limit that was sensible at onboarding can become too restrictive or too permissive, and a dormant integration exception can quietly become the normal route. Periodic review should close expired overrides and verify approvers.
Contact StoreBuilt if your Shopify B2B project needs credit and order states mapped before development.
StoreBuilt point of view
StoreBuilt believes B2B ecommerce should remove purchasing friction without hiding financial exposure. The best workflow gives a good account a fast, predictable route to order while making uncertainty and exceptions visible to both buyer and operator. The integration should enforce an agreed credit policy; it should never be asked to invent one.
For a B2B workflow and integration review, Contact StoreBuilt.